
Prop 37 creates a California loan that can cover up to 17% of a newly built home’s price, so a buyer with 3% of their own money can reach a full 20% down. CalHFA has until about the end of 2027 to open it, and nobody can apply yet.
What Is the Prop 37 Home Loan?
It’s a second mortgage from the state, and it only works on brand-new homes. You bring at least 3% of the price from your own savings, the state loan covers up to 17%, and a first mortgage carries the remaining 80% (Legislative Analyst’s analysis). That 3% and 17% shape narrows the first loan, too. In practice it points to a conventional loan, the kind Fannie Mae and Freddie Mac buy.
CalHFA, the state’s housing finance agency, runs it. The state pays for it by selling up to $25 billion in revenue bonds, and the monthly payments buyers make on the loan pay those bonds back. The Legislative Analyst found no direct cost to taxpayers.
The measure calls it the “middle-class homeownership loan,” though CalHFA will probably give it a catchier name at launch.
Did Prop 37 Pass, and When Can I Apply?
As of November 4, 2026, the Associated Press projects Prop 37 passed with about 61% of the vote (results). The count isn’t final until the Secretary of State certifies it in December.
The law takes effect five days after that certification, and from then CalHFA has up to one year to open the program (measure text, Section 51515.05). It has to write the rules first: the interest rate, the loan term, the payment schedule, the credit score floor. So the realistic window is sometime in 2027, and there’s no application to fill out today. We’ll update this page the day CalHFA publishes its rules.
Who Qualifies for the Prop 37 Loan?
The measure sets these rules (measure text). CalHFA can add more.
| Rule | What the measure says |
|---|---|
| California resident | At least 1 year before you apply |
| Live in it | Your primary residence, moved in within 60 days of closing |
| Income | Up to 200% of the area median income for your county, by family size |
| Your down payment | At least 3% of the price, your own money |
| A real estate agent | A licensed California agent you choose |
| First-time buyer? | Not required |
That last row matters. Unlike most state help, you don’t have to be a first-time buyer. A family that owns today and wants a bigger new home can use it, as long as the income limit fits.
The 3% rule matters too. It has to be your money. A gift or another assistance program can’t count toward that 3%, so this loan doesn’t stack with programs that cover your whole down payment.
Which Homes Qualify?
Only new ones, and you have to be the first buyer:
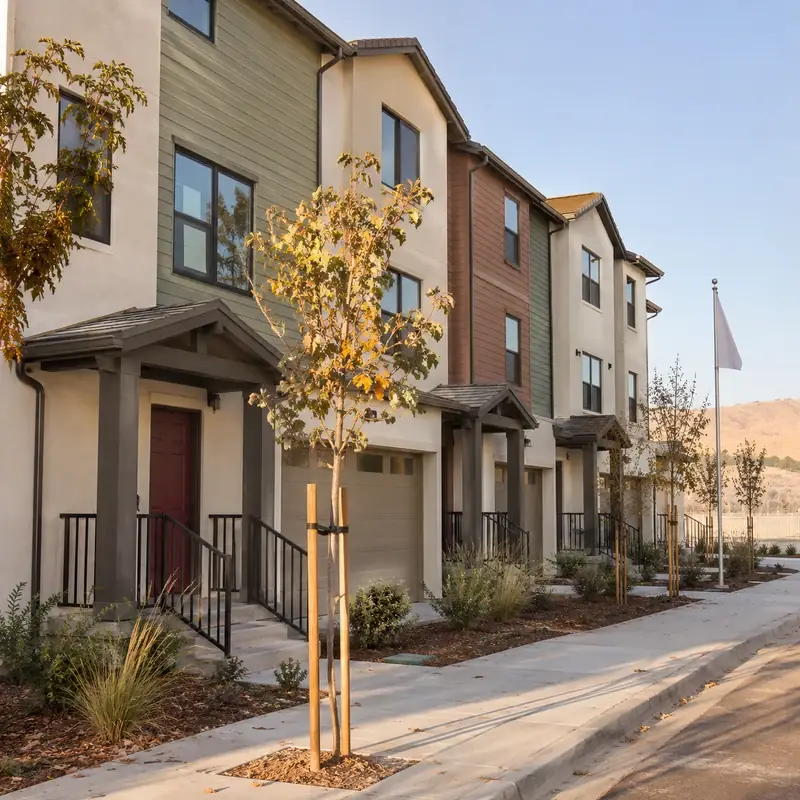
- a newly built house, townhome, row house or condo
- a new manufactured home
- a condo or home in a building that used to be offices or stores and was converted
The price has a cap: 125% of the county’s one-unit conforming loan limit. With the 2026 limits from the Federal Housing Finance Agency, that’s $1,040,937 in most California counties and up to $1,561,406 in the highest-cost counties. FHFA sets new limits for 2027 in late November, and the limit in force when you buy is the one that counts.
Who Does Prop 37 Really Help?
It’s aimed at middle-income California families, and the income limit keeps it there, which could do a lot of good.
The catch is the homes. Resales make up the vast majority of sales, in California and nationwide, and new construction is a much smaller slice of the market. So if the house you want sits in an established neighborhood you already love, Prop 37 can’t help you buy it.
The money has a ceiling, too. $25 billion sounds enormous until you divide it by everyone who wants a piece: at $136,000 a loan (the 17% on an $800,000 home), it covers about 184,000 buyers. State help tends to run dry fast. Dream For All, the last big one, is closed to new applications today.
Builders come out of it well, since only newly built homes count and the measure lets builders sign up as “qualified builders” whose developments count automatically (Legislative Analyst’s analysis). The way we see it, this looks like a measure written by and for new-home builders, and it helps them more than it helps most buyers.
We offer every CalHFA program and will use this one when it fits. Mostly, though, we like other down payment help better. Our no money down grant covers the down payment, is forgiven after six on-time payments and works on resales. For a buyer who earns too much for CalHFA, FHA first-and-second programs go up to 101.5% of the price with no income limits.
How the Numbers Work on a New Home
Take an $800,000 new townhome:
| Piece | Share | Amount |
|---|---|---|
| Your money | 3% | $24,000 |
| Prop 37 loan | 17% | $136,000 |
| Your first mortgage | 80% | $640,000 |
Here’s the part most people miss. An 80% first mortgage sits right where a conventional loan usually stops needing private mortgage insurance. The price cap lines up with the loan limits too: 80% of the cap equals the county’s conforming limit, so the first mortgage stays a regular conforming loan and never has to be a jumbo.
You’ll make two monthly payments, one on each loan. What the Prop 37 loan will cost each month is still unknown. The measure only says its terms must be fixed, CalHFA must keep borrowers’ costs as low as it can, and there’s no prepayment penalty.
The measure also limits what the lender can charge to set the loan up: an origination fee of no more than 0.5% of the loan or $290, whichever is more (measure text).
How Does Prop 37 Compare to Other Help?
As of November 2026, from CalHFA’s program pages:
| Prop 37 loan | Dream For All | CalHFA MyHome | |
|---|---|---|---|
| Homes | New homes only | Any eligible home | Any eligible home |
| Size | Up to 17% | Up to 20% | Up to 3.5% (FHA) |
| Monthly payment | Yes | No, repaid when you sell or refinance | No, repaid when you sell or refinance |
| First-time buyers only | No | First-generation buyers | Yes |
| Open now | No, opens by about the end of 2027 | Closed to new applications since March 16, 2026 | Yes |
The big difference is the monthly payment. Dream For All and MyHome wait until you sell or refinance. Prop 37 gets paid back month by month, which is how it pays for itself without the state’s budget.
What Did Prop 1 Do for Homebuyers?
Prop 1, the $11.25 billion housing bond, also passed by the AP’s projection with about 59% of the vote (results), and most of its money pays for apartments (Legislative Analyst’s analysis). Buyers don’t get a new loan out of it, though. What they get is more money in programs that already exist (the bond’s text, SB 417):
- $500 million to CalHFA’s home purchase assistance fund, the money behind its down payment help
- $600 million to CalHome, which local agencies and nonprofits use for buyer loans, self-help building and manufactured homes
- $1.25 billion for CalVet home loans for veterans, repaid by the veterans’ own payments
CalHFA decides which of its programs get the new money, and when. The bond never names Dream For All, so don’t count on it reopening because of Prop 1. When CalHFA announces where the money goes, our CalHFA programs guide will show it.
Should You Wait for Prop 37 or Buy Now?
We wouldn’t wait for it. Government programs are notorious for delays, and this one hasn’t even written its rules. Use Prop 37 if it happens to be open when you’re ready to buy, and if it isn’t, find the home you love and buy that one.
Here’s what works today, on new builds and resales alike:
| If you are | Look at |
|---|---|
| Short on the down payment | Our no money down program, an FHA or conventional loan with a grant for the down payment, forgiven after six on-time payments |
| On FHA and want the 3.5% covered | The Elite Grant, a grant forgiven in 6 to 36 months |
| Over CalHFA’s income limits | An FHA first-and-second program up to 101.5% of the price, no income limits |
| Working on your credit | FHA, 3.5% down |
| A veteran or service member | VA, nothing down |
| Building on your own lot | Construction-to-permanent, the build and the mortgage in one loan |
| Selling a home you own now | Buy before you sell, so you can move first |
A conventional loan with 3% down works on most new builds too, and plenty of buyers in new subdivisions use one. For every route to a home with little or nothing down, see how to buy a house with no money down.
Still want Prop 37 in your plan? Get pre-approved now anyway, because it tells you where your income sits against the 200% limit, what price range fits under the cap and how big your 3% really is. Pre-approval is usually within 24 hours once we have your documents.
Is Prop 37 a Good Deal?
For some buyers. Getting to 20% down on a $930,000 home normally means saving $186,000 (official voter guide), and Prop 37 cuts the cash you need to 3%.
The trade-offs are real, and we’d tell you about them across the desk:
- The 17% loan carries its own monthly payment on top of your mortgage, so you qualify for two payments, not one.
- Only new homes count, and a lot of new subdivisions sit at the edges of the metros, farther from jobs and transit.
- Nobody knows the rate. CalHFA sets it, and what bond buyers will accept drives it.
- In the priciest counties, plenty of new homes list above the $1.56 million cap.
- Watch the price. A new home that needs Prop 37 to pencil out can cost more than a resale in a more established neighborhood, so compare the two before you sign.
- Know the repayment rules once CalHFA writes them. If you’re comfortable with them, great. If you’re not, don’t use it. Other programs are available.
We’ll run your numbers both ways, Prop 37 against a loan you can use today, as soon as CalHFA publishes its terms.